What is the scope and industry significance of the Medical Textile Market?
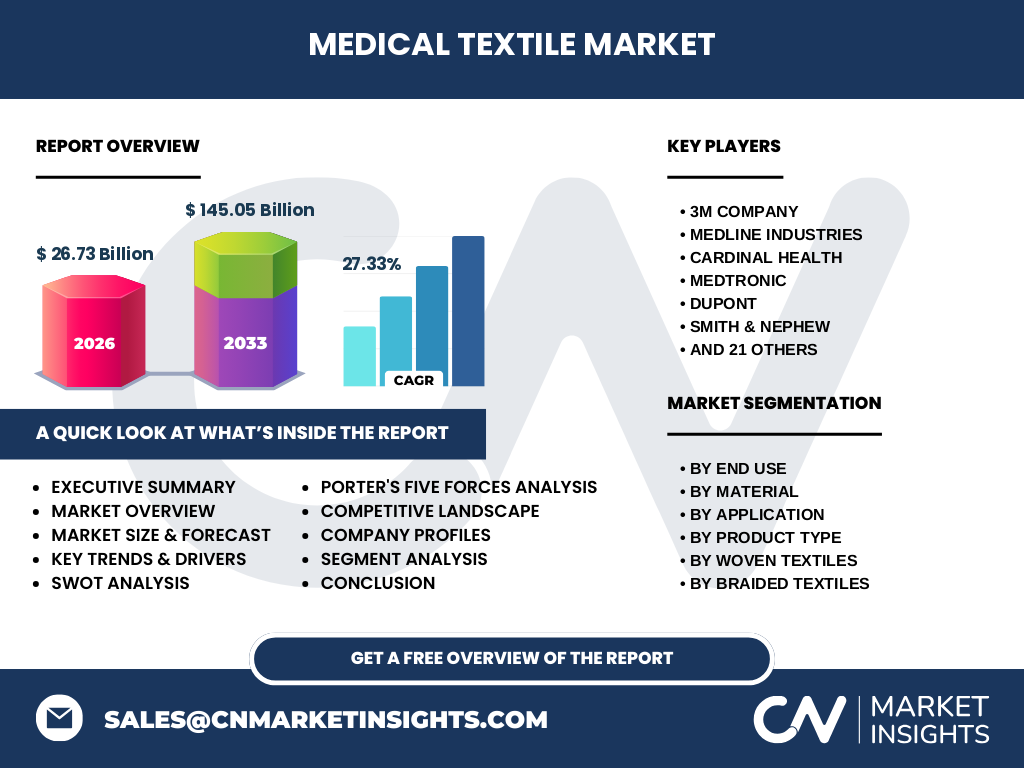
Our analysis indicates that the Medical Textile Market encompasses high-performance materials utilized across healthcare facilities and home settings. Valued at 26.73 Billion in 2026, this sector is anchored by stringent regulatory frameworks from bodies like the FDA and EMA. Industry significance lies in infection control, surgical efficacy, and patient rehabilitation, utilizing advanced raw materials such as polypropylene, biodegradable polymers, and specialized natural fibers.
Structural Growth Drivers and Restraints in the Medical Textile Market
The data suggests that the market is propelled by an aging global demographic and rising surgical volumes, driving demand for Surgical And Implantable Products and Wound Care Products. Conversely, stringent sterilization protocols and fluctuating raw material costs for Synthetic Polymers act as primary restraints. Compliance with ISO and CE certification standards creates notable market entry barriers for emerging manufacturers.
Emerging Trends and Growth Patterns in Medical Textile Market industry trends
A pivotal shift toward sustainability is reshaping the Medical Textile Market industry trends, with surging adoption of Biodegradable Materials and eco-friendly Nonwoven Textiles. Manufacturers are increasingly integrating antimicrobial finishes into Protective Apparel to combat hospital-acquired infections, favoring vertically integrated innovators capable of scaling sustainable production without compromising tensile strength or fluid barrier performance.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic triggered unprecedented demand for Protective Apparel and Nonwoven Textiles, straining global supply chains anchored by key ports in Asia and North America. Our research reveals that post-pandemic recovery has stabilized supply channels while permanently elevating baseline demand for Medical Textile Market solutions, forcing companies like 3M Company and DuPont to diversify manufacturing footprints to mitigate future logistical bottlenecks.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high market concentration among established leaders such as Medtronic, Cardinal Health, and Mölnlycke Health Care. Strategic dynamics heavily favor firms investing in R&D for advanced Surgical And Implantable Products. Mergers, acquisitions, and regional facility expansions represent core strategies used by major players to secure proprietary raw material access and outpace regional competitors.
Executive Summary: High-Level Findings on the Medical Textile Market
Our comprehensive evaluation highlights a massive expansion phase for the Medical Textile Market, projected to surge from 26.73 Billion in 2026 to an astounding 145.05 Billion by 2033 at a phenomenal CAGR of 27.33%. This exponential trajectory is driven by technological advancements in Woven Textiles and Knitted Textiles, alongside escalating healthcare expenditures across emerging economies.
Market Forecast and Long-Term Projections from 2027 to 2033
Based on our research, the Medical Textile Market will expand aggressively from 2027 through 2033, culminating in a market valuation of 145.05 Billion. This stellar 27.33% CAGR reflects accelerating demand across Hospitals And Clinics as well as expanding Home Healthcare Settings, rewarding stakeholders who prioritize high-margin specialized product innovations.
Segmentation Analysis: Breaking Down Core Product and Application Categories
Market architecture is divided across multiple tiers. End uses span Hospitals And Clinics, Ambulatory Surgical Centers, and Home Healthcare Settings. Materials include Natural Fibers, Synthetic Polymers, and Biodegradable Materials. Applications cover Surgical And Implantable Products and Wound Care Products. Product types feature Nonwoven Textiles, Woven Textiles, Knitted Textiles, and Braided Textiles.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading consumption due to advanced healthcare infrastructure and stringent safety mandates. Meanwhile, Asia-Pacific represents the fastest-growing regional market, driven by expanding manufacturing hubs in China and India, localized healthcare modernization initiatives, and increasing procedural volumes in urban hospitals.
In-Depth Regional Review of High-Growth Healthcare Hubs
Our analysis indicates that North America maintains dominance through high adoption rates of advanced Surgical And Implantable Products and rigorous FDA oversight. Concurrently, the Asia-Pacific region capitalizes on cost-efficient manufacturing of Nonwoven Textiles and Protective Apparel, leveraging robust supply chains tied to major maritime ports and favorable regional trade agreements.
Company Profiles and Strategic Positioning of Leading Industry Innovators
Industry leaders occupy distinct market niches. 3M Company and Medtronic dominate high-end Surgical And Implantable Products, while Berry Global and Ahlstrom specialize in scalable Nonwoven Textiles. Companies like Mölnlycke Health Care and Smith & Nephew focus heavily on advanced Wound Care Products, leveraging strong distributor networks and clinical validation to maintain pricing power.
Porter's Five Forces Analysis of the Medical Textile Market
Competitive rivalry is intense among established conglomerates, while the threat of new entrants remains moderate due to steep regulatory hurdles and capital-intensive manufacturing setups. Bargaining power of suppliers is tempered by diverse raw material options like Synthetic Polymers and Natural Fibers, whereas buyer power is balanced by strict clinical quality requirements.
SWOT Analysis Highlighting Strategic Strengths and Vulnerabilities
Strengths include robust intellectual property portfolios and high barriers to entry for Surgical And Implantable Products. Weaknesses involve high sensitivity to raw material price volatility. Opportunities lie in expanding Home Healthcare Settings, while threats include stringent, evolving international regulatory compliance standards enforced by bodies like the European Medicines Agency.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with chemical and fiber producers supplying Synthetic Polymers and Natural Fibers. Midstream processors convert these inputs into Knitted Textiles, Braided Textiles, and Nonwoven Textiles. Downstream, converters and distributors supply finished Hospitals And Clinics, ensuring compliance with strict sterilization and biocompatibility protocols.
Investment Insights and High-Potential Growth Pockets
The data suggests stellar investment potential in companies pioneering Biodegradable Materials and smart textiles embedded with diagnostic sensors. Investors should target mid-sized manufacturers supplying Ambulatory Surgical Centers and Home Healthcare Settings, as these decentralized care models exhibit faster adoption curves than traditional hospital infrastructure.
Conclusion and Strategic Takeaways for Industry Stakeholders
Reaching 145.05 Billion by 2033 at a 27.33% CAGR, the Medical Textile Market offers extraordinary growth for agile participants. Success demands continuous R&D investment in sustainable Nonwoven Textiles and stringent regulatory compliance, positioning forward-thinking firms to capture expanding market share across global healthcare networks.
Research Methodology and Baseline Triangulation Techniques
Our findings are derived from a rigorous triangulation methodology. We combine primary stakeholder interviews with C-level executives, extensive secondary research from trade registries, and macroeconomic indicators. Baseline estimates for 2026 at 26.73 Billion are cross-verified against import-export data from major global ports and regulatory filings.
Scope of the Report and Analytical Parameters
This report evaluates the global Medical Textile Market across defined parameters, covering market sizing from 2026 through the forecast horizon of 2033. It analyzes detailed segmentations spanning materials, applications, product types, and end uses, while explicitly noting regional regulatory constraints and macroeconomic variables impacting the sector.
Recent Developments, Product Launches, and Strategic Partnerships
Recent industry momentum features aggressive capacity expansions by market leaders such as Berry Global and Freudenberg Group in sustainable Nonwoven Textiles. Furthermore, strategic acquisitions among firms producing Surgical And Implantable Products highlight an industry-wide push to consolidate technological capabilities and expand geographic footprints in emerging healthcare markets.